



Individual & AOP Tax · United StatesPersonal returns for US business owners, and partnership returns for what Pakistan would call an AOP.
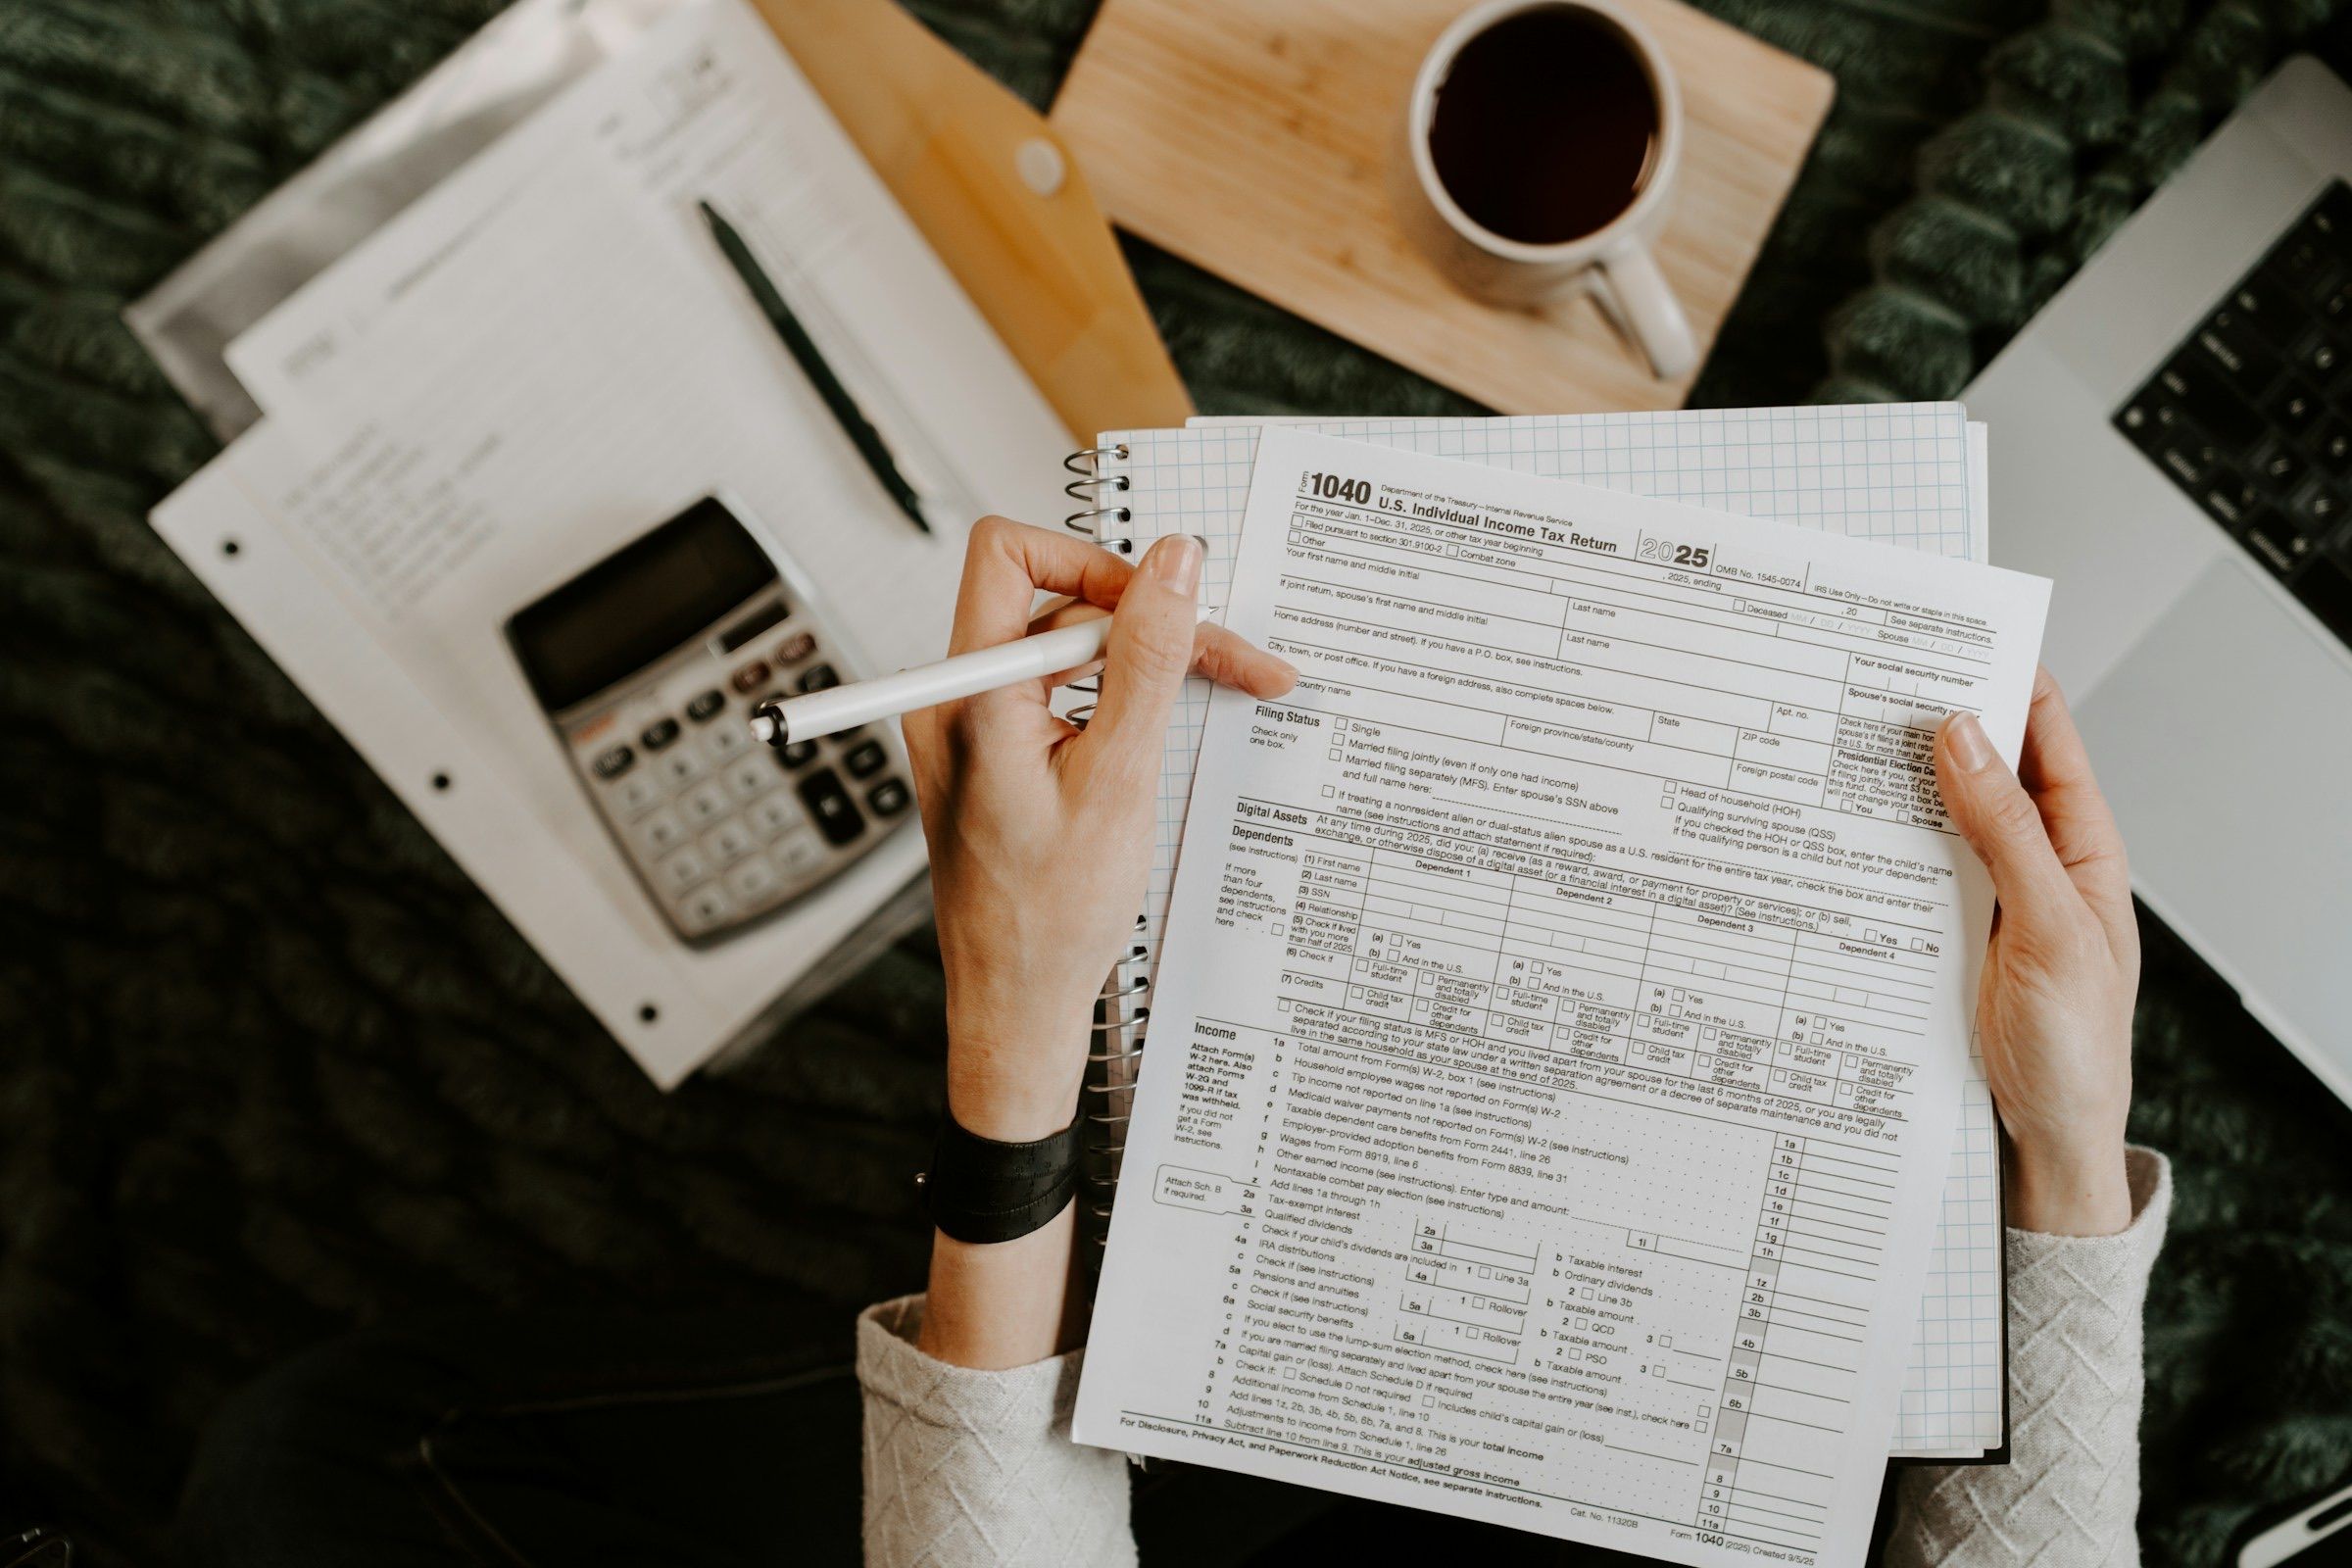
We prepare Forms 1040 and 1040-NR for owners and sole proprietors, and Form 1065 with Schedules K-1 for partnerships and multi-member LLCs.
Tax
At a glance
- Authorities
- Internal Revenue Service (IRS) · Financial Crimes Enforcement Network (FinCEN) · State departments of revenue
- Forms & references
- Form 1040Form 1040-NRSchedule CSchedule SEForm 1065
- Residents and citizens
- Form 1040, reporting worldwide income
- Nonresidents
- Form 1040-NR, reporting US-source and effectively connected income
- Partnerships and multi-member LLCs
- Form 1065 by March 15 (calendar year), with a Schedule K-1 for each partner
- Individual deadline
- April 15; Form 4868 extends filing (not payment) to October 15
Overview
What it is, and why it matters.
Your residency decides your return. US citizens and resident aliens (green card holders, or people who meet the substantial presence test) file Form 1040 and report worldwide income. Nonresident aliens file Form 1040-NR and generally report only US-source income and income effectively connected with a US business.
A sole proprietor, or the US owner of a single-member LLC, reports business profit on Schedule C. On top of income tax, net self-employment earnings are generally subject to self-employment tax of 15.3% for Social Security and Medicare, calculated on Schedule SE, with the Social Security part capped each year.
In Pakistan, an association of persons (AOP) is a taxable unit: the firm files its own return and pays tax on its income. The US has no AOP category. The closest equivalent is a partnership, which by default includes a multi-member LLC. It files Form 1065 but usually pays no federal income tax itself. Each partner receives a Schedule K-1 and pays tax on their share of profit, whether or not the cash was distributed.
When a partnership has foreign partners and income effectively connected with a US business, it must generally withhold tax on their shares under section 1446, at the highest rate for that type of partner (37% for individuals and 21% for corporations at the time of writing), reported on Forms 8804 and 8805. Foreign partners then file their own US return to settle the actual liability.
Who needs it
Who typically needs it.
- 01
Pakistani and other non-US partners in US businesses
Members of a US LLC or partnership who receive a K-1 and need to file Form 1040-NR.
- 02
Sole proprietors and single-member LLC owners
US-resident freelancers, consultants and small business owners who report business income on Schedule C.
- 03
Partnerships and multi-member LLCs
Two or more owners running a business together, including family businesses that would be an AOP in Pakistan.
- 04
New US residents
Founders and employees who have moved to the US and must now report worldwide income and foreign accounts.
- 05
S corporation shareholders
US-resident owners whose personal return depends on the K-1 from their company and who want the two prepared together.
When you need it
The moments that usually trigger it.
- You and a partner have formed a US LLC and want to know how it is taxed and what each of you files.
- You’ve received a Schedule K-1 from a US partnership and you live outside the US.
- You moved to the US this year and aren’t sure whether you are a resident or a nonresident for tax.
- Your freelance or consulting income has grown and you haven’t paid estimated tax.
- You hold bank accounts in Pakistan or elsewhere and have become a US tax resident.
- Your partnership has a foreign partner and nobody has looked at section 1446 withholding.
Scope
Exactly what we handle.
Our engagement letter lists these specifically, so you know what is included before any work begins.
- 01
Determining residency status, including the substantial presence test and first-year or dual-status situations.
- 02
Preparing Form 1040 with Schedules C and SE for sole proprietors and single-member LLC owners.
- 03
Preparing Form 1040-NR for nonresident partners and business owners, including treaty positions where one is available.
- 04
Preparing Form 1065 and Schedules K-1 for partnerships and multi-member LLCs.
- 05
Section 1446 withholding calculations, payments on Form 8813 and annual Forms 8804 and 8805 for partnerships with foreign partners.
- 06
Quarterly estimated tax (Form 1040-ES) for owners and self-employed clients.
- 07
Foreign account reporting for US persons: FinCEN Form 114 (FBAR) and Form 8938 where required.
- 08
Coordinating an ITIN application when a partner or spouse needs one to file.
The process
How it runs, step by step.
Timings depend on the authority and on how quickly documents come together. We tell you what’s typical for your case at the start.
Start with a conversationStatus and structure
We confirm each person’s residency status and how any business is classified, and list which returns each owner files.
Information gathering
You complete a questionnaire and upload income records, K-1s, business figures and prior returns.
Partnership return first
For partnerships, we prepare Form 1065 and the K-1s before the partners’ personal returns, because those depend on them.
Personal returns
We prepare Form 1040 or 1040-NR for each owner, with state returns where needed.
Review, sign and file
You review the drafts and sign the e-file authorization, and we file and send you the confirmations.
Plan for next year
We set estimated tax amounts and note any residency or ownership changes to watch for.
What we’ll need
The information to have ready.
A typical checklist. After the first conversation we send a version specific to your situation, so you don’t gather anything you don’t need.
Identity and status
- SSN or ITIN for each person filing
- Passport and US visa or green card details
- Days spent in the US this year and in the two previous years (nonresidents and new residents)
Income
- Forms W-2, 1099 and K-1 received
- Business income and expenses for Schedule C
- Foreign income and foreign taxes paid (residents)
Partnership records
- LLC operating agreement or partnership agreement
- Capital contributions, distributions and each partner’s profit share
- Partner addresses, countries and tax IDs, with Forms W-9 or W-8BEN
Other
- Prior-year returns
- Highest balances of foreign bank and financial accounts (residents)
- Estimated tax payments already made
Please don’t email passports or bank statements. Once we’ve spoken, you’ll get access to a secure upload.
Common mistakes
Where this usually goes wrong.
The problems we are most often asked to fix, and what they tend to cost.
- Mistake 01
Expecting a multi-member LLC to pay tax like an AOP
By default a multi-member LLC files Form 1065 and pays no federal income tax itself. Each partner is taxed on their share of profit, even if no cash was distributed.
- Mistake 02
Filing the wrong form for your residency
A nonresident filing Form 1040, or a resident filing Form 1040-NR, reports the wrong income and claims the wrong deductions. Fixing it later means amended returns and possible penalties.
- Mistake 03
Missing section 1446 withholding
A partnership that fails to withhold on a foreign partner’s share of effectively connected income can be held liable for that tax, plus penalties and interest.
- Mistake 04
Overlooking the FBAR
US persons whose foreign accounts total more than $10,000 at any time in the year must file FinCEN Form 114. Penalties for not filing can be severe, even when no tax is owed.
Worth knowing
The limits, stated upfront.
Residency and treaty positions depend on facts only you can confirm, such as travel days and personal ties. We rely on the information you provide.
Pakistani returns filed with the FBR are not part of this service. See our Pakistan pages for those.
Immigration questions, such as how a business affects a visa, need an immigration attorney.
Trusts, estates and complex cross-border structures may need a specialist adviser.
State residency rules differ from federal rules and are assessed state by state.
Questions
Individual & AOP Tax: frequently asked.
If yours isn’t here, ask us directly. We’ll answer in plain terms.
Ask a questionWhat is the US equivalent of an AOP?
The closest US equivalent is a partnership, which includes a multi-member LLC unless it elects to be taxed as a corporation. Unlike an AOP in Pakistan, a partnership usually pays no federal income tax itself; it files Form 1065 and passes profit to partners on Schedule K-1. Each partner then pays tax on their share on their own return.
I live in Pakistan and own part of a US LLC. What do I file?
If the LLC is a partnership earning income effectively connected with a US business, you generally file Form 1040-NR to report your share and claim credit for any tax the LLC withheld under section 1446. Some states expect a nonresident return as well. You need an SSN or ITIN to file.
Do nonresidents pay US self-employment tax?
Generally no. Nonresident aliens are usually not subject to US self-employment tax, although income tax can still apply to effectively connected business income. That changes if you become a US resident for tax purposes.
When is Form 1040-NR due?
If you received wages subject to US withholding, Form 1040-NR is generally due April 15. If not, it is generally due June 15. Form 4868 extends the time to file but not the time to pay.
How do I know if I am a US tax resident?
You are generally a resident if you hold a green card or meet the substantial presence test: at least 31 days in the US this year and 183 days over three years, counting all days this year, one third of last year’s days and one sixth of the year before. Some visa holders do not count certain days, and a tax treaty can change the result.
Does a single-member LLC file its own income tax return?
Not usually. A single-member LLC owned by a US person is disregarded for income tax and reported on the owner’s Form 1040, typically on Schedule C. If the owner is foreign, the LLC files a pro forma Form 1120 with Form 5472 instead.
Related
Often needed alongside this.

The equivalent in our other countries
Speak with a consultant
Talk to us about individual & AOP Tax.
Pick the closest match and we’ll take it from there. You’ll get a written scope and fee before any work begins.
Or use our three-step guide, or email hello@fiscorra.com
