



Corporate Tax · United StatesYour corporation’s tax bill is mostly decided before the year ends. We prepare the return and help with the decisions that come before it.
We prepare Forms 1120 and 1120-S, handle estimated tax and foreign-ownership reporting, and file the state corporate returns that go with them.
Tax
At a glance
- Authorities
- Internal Revenue Service (IRS) · State departments of revenue
- Forms & references
- Form 1120Form 1120-SForm 2553Form 5472Form 7004
- Federal rate (C corporation)
- Flat 21% at the time of writing
- Due dates (calendar year)
- Form 1120: April 15. Form 1120-S: March 15
- Extension
- Form 7004, generally six months to file (not to pay)
- Estimated tax
- C corporations pay by the 15th of the 4th, 6th, 9th and 12th months of the tax year
Overview
What it is, and why it matters.
A C corporation is a separate taxpayer. It files Form 1120 and pays federal income tax at a flat 21% on its taxable income, and shareholders pay tax again on dividends they receive. Most states add their own corporate income or franchise tax.
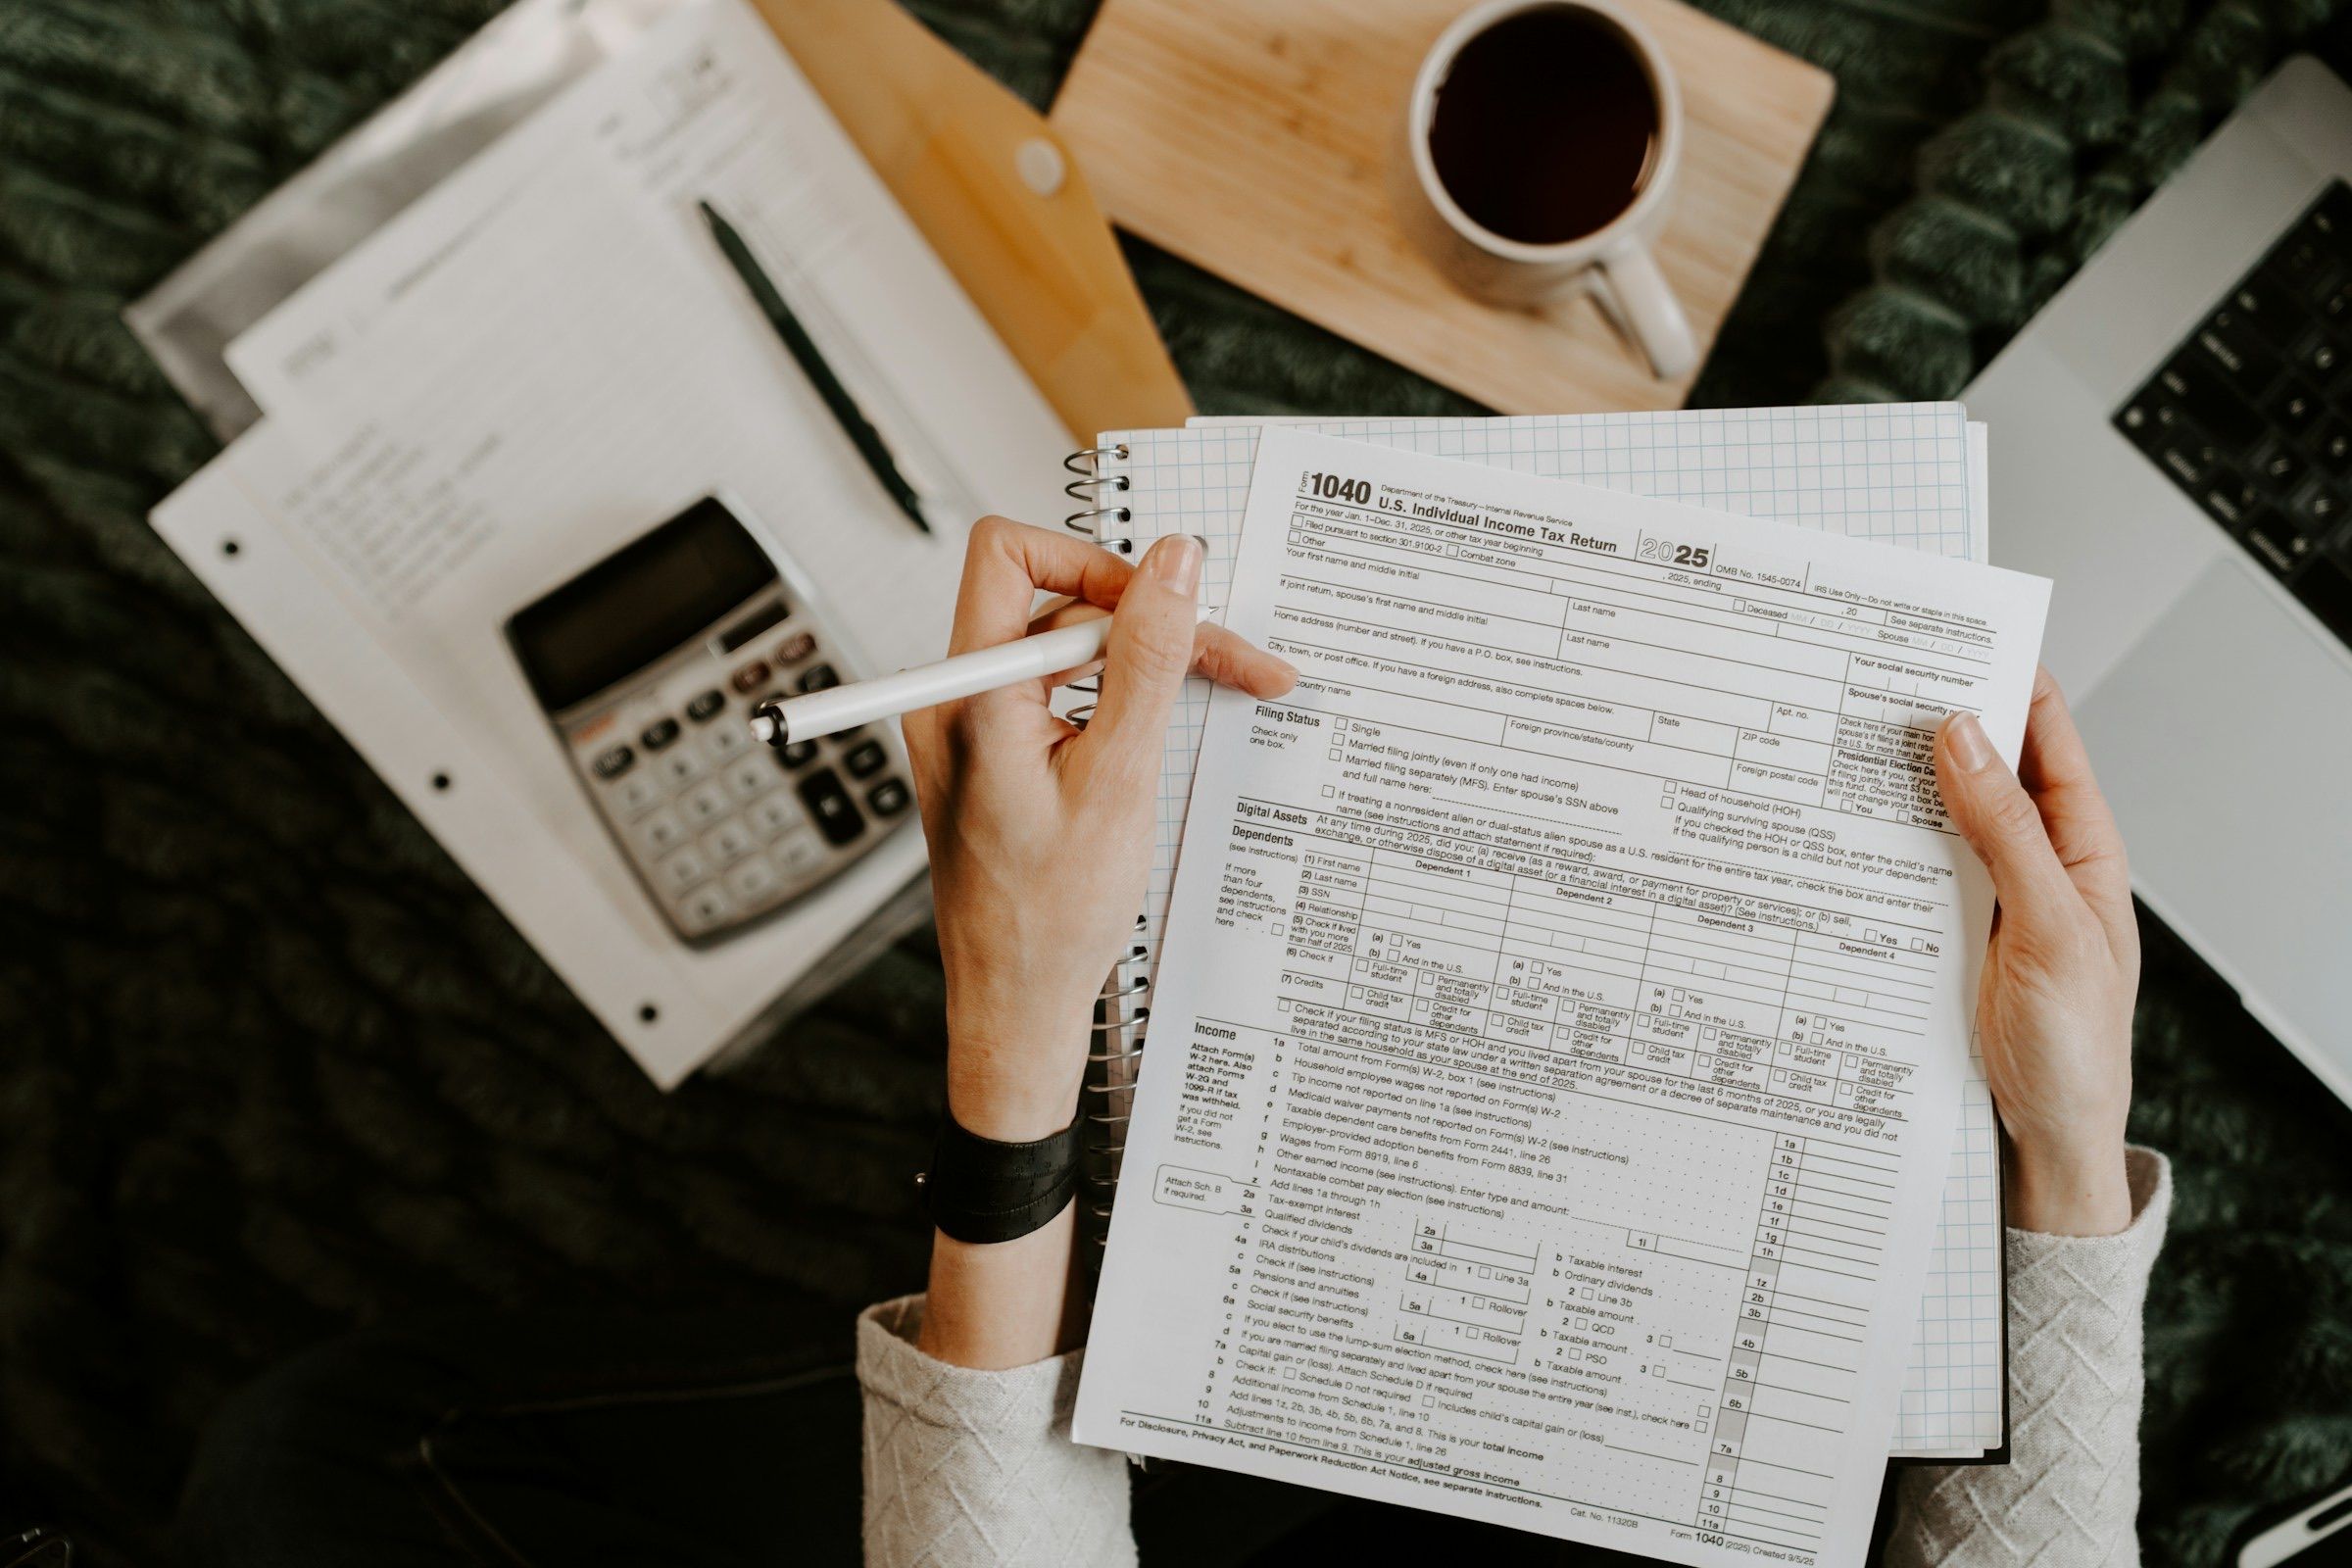
An S corporation files Form 1120-S but usually pays no federal income tax itself. Profit passes to shareholders on Schedule K-1 and is taxed on their personal returns. S status needs a timely Form 2553 election and has strict eligibility rules: no more than 100 shareholders and no nonresident alien shareholders, which rules it out for many founders based outside the US.
Compliance is the return. Planning is the set of decisions that shape it: when income and expenses fall, how owners are paid, whether a fiscal year suits you, and how new law applies. For example, the 2025 federal tax law restored the immediate deduction of domestic research and experimental costs from 2025. We do both, and keep them separate so you know which conversation you are having.
Who needs it
Who typically needs it.
- 01
Startup C corporations
Delaware C corporations with investors, option plans or early losses that still need accurate federal and state returns every year.
- 02
Owner-managed S corporations
US-resident owners who elected S status and need owner salary, distributions and K-1s handled correctly.
- 03
Foreign-owned US corporations
Companies owned by founders or parent companies in Pakistan, the UK or elsewhere, which need Form 5472 and care over related-party transactions.
- 04
LLCs taxed as corporations
LLCs that elected C or S corporation treatment and now file Form 1120 or 1120-S.
- 05
Corporations considering a change
Owners weighing an S election or revocation, a fiscal year change, or a conversion before a fundraise or sale.
When you need it
The moments that usually trigger it.
- Your corporation has finished its first tax year and the Form 1120 or 1120-S deadline is approaching.
- You expect a profitable year and haven’t made any estimated tax payments.
- You want to elect S corporation status and need to know whether you qualify and when Form 2553 must be filed.
- A foreign shareholder has lent money to the US company, or charged it fees.
- You’re raising investment and the investor’s due diligence asks for filed returns.
- You’ve received an IRS notice for underpaid estimated tax or a late S corporation return.
Scope
Exactly what we handle.
Our engagement letter lists these specifically, so you know what is included before any work begins.
- 01
Preparing and e-filing Form 1120 or Form 1120-S with supporting schedules, including Schedules K-1 for S corporation shareholders.
- 02
Form 5472 for corporations at least 25% foreign-owned, with a record of the related-party transactions reported.
- 03
Quarterly estimated tax calculations for C corporations, based on current-year projections or the prior-year safe harbor where it is available.
- 04
Form 7004 extensions with an estimate of the balance due.
- 05
S corporation elections on Form 2553, including late-election relief requests where the facts support them.
- 06
A reasonable compensation review for S corporation owner-employees, coordinated with payroll.
- 07
State corporate income and franchise tax returns, including apportionment across states.
- 08
Year-end planning meetings on timing of income and expenses, owner pay, and how recent law changes affect your numbers.
The process
How it runs, step by step.
Timings depend on the authority and on how quickly documents come together. We tell you what’s typical for your case at the start.
Start with a conversationYear-end review
Before the year closes, we look at projected profit, owner pay and any decisions still open.
Close the books
Your books are reconciled and closed, and we review the trial balance and fixed asset records.
Prepare the returns
We prepare Form 1120 or 1120-S, Form 5472 if needed, and the state returns, with a list of any open questions.
Review with you
We walk through the result, the tax due or refund, and what it means for next year’s estimated payments.
File and schedule
Returns are e-filed, K-1s go to shareholders, and next year’s estimated payment dates are set.
What we’ll need
The information to have ready.
A typical checklist. After the first conversation we send a version specific to your situation, so you don’t gather anything you don’t need.
Corporate records
- Articles of incorporation, bylaws and cap table or shareholder register
- IRS acceptance letter for any S election (Form 2553)
- Prior-year federal and state returns
Financials
- Year-end trial balance, profit and loss statement and balance sheet
- Fixed asset purchases and disposals
- Loan agreements, including loans to or from shareholders
Payroll and owners
- Payroll reports (Forms W-2 and 941) and officer compensation
- Dividends or distributions paid during the year
Foreign ownership (if applicable)
- Names, countries and tax IDs of shareholders owning 25% or more
- Intercompany agreements and a list of payments to or from related foreign parties
Please don’t email passports or bank statements. Once we’ve spoken, you’ll get access to a secure upload.
Common mistakes
Where this usually goes wrong.
The problems we are most often asked to fix, and what they tend to cost.
- Mistake 01
Electing S status with an ineligible shareholder
A nonresident alien shareholder, a corporate shareholder or a second class of stock can invalidate or terminate an S election, often unnoticed until an IRS letter arrives.
- Mistake 02
Skipping estimated tax in a profitable year
C corporations expecting to owe $500 or more for the year must pay in quarterly installments. Underpayment triggers a penalty calculated on Form 2220.
- Mistake 03
Paying S corporation owners only through distributions
An owner who works in the business should receive reasonable wages through payroll. Treating all pay as distributions is a well-known IRS audit issue.
- Mistake 04
Leaving related-party transactions undocumented
Loans, management fees and cost recharges between a US corporation and its foreign owner must be reported on Form 5472 and priced at arm’s length. A missing Form 5472 carries a $25,000 penalty.
Worth knowing
The limits, stated upfront.
We do not give legal opinions on corporate structure, securities or reorganizations. Those need a corporate attorney.
Transfer pricing studies for significant cross-border related-party transactions are outside standard scope and may need a specialist.
Planning is based on current law and the facts you give us. Law changes and IRS interpretations can alter the result.
Where books are incomplete, clean-up bookkeeping is needed before the return can be prepared.
Questions
Corporate Tax: frequently asked.
If yours isn’t here, ask us directly. We’ll answer in plain terms.
Ask a questionWhat is the federal corporate tax rate?
C corporations pay a flat 21% federal income tax on taxable income at the time of writing. State corporate taxes are additional and vary by state. S corporations generally pay no federal income tax at the entity level.
Can a founder who lives in Pakistan own an S corporation?
Generally no. S corporation shareholders must be US citizens or residents (or certain trusts and estates), so a nonresident alien shareholder makes the company ineligible. Foreign founders usually use a C corporation or an LLC instead, and we can walk through the tax effect of each.
When are a C corporation’s estimated tax payments due?
Installments are due by the 15th day of the 4th, 6th, 9th and 12th months of the tax year, so April 15, June 15, September 15 and December 15 for a calendar-year corporation. They are required when the corporation expects to owe $500 or more for the year.
Can my corporation use a fiscal year instead of the calendar year?
A C corporation can generally choose a fiscal year when it files its first return. S corporations usually must use the calendar year unless they show a business purpose or make a section 444 election. Changing an established year typically needs IRS approval on Form 1128.
Does my corporation need to file if it had no income?
Yes. A corporation must file Form 1120 or Form 1120-S for every year it exists, even with no income, until it is formally dissolved. Most states also expect returns or minimum taxes until the entity is closed with them.
Do dividends paid to a foreign shareholder need withholding?
Usually, yes. Dividends a US corporation pays to a foreign shareholder are generally subject to 30% withholding unless a tax treaty reduces the rate, reported on Forms 1042 and 1042-S. We check treaty eligibility and documentation, such as Form W-8BEN, before the payment is made.
What is the difference between tax planning and tax compliance?
Compliance is preparing and filing the returns you owe, accurately and on time. Planning is looking ahead at choices that affect the tax, such as entity status, owner pay and timing, while they can still be changed. We scope them as separate pieces of work so it is clear what each covers.
Related
Often needed alongside this.

The equivalent in our other countries
Speak with a consultant
Talk to us about corporate Tax.
Pick the closest match and we’ll take it from there. You’ll get a written scope and fee before any work begins.
Or use our three-step guide, or email hello@fiscorra.com
